10 Personal Finance Lessons That Actually Build Wealth (No Fluff, Just What Works)
Real personal finance lessons that separate people who build wealth from people who just look wealthy.
Why Most Money Advice Sounds Good But Goes Nowhere
The Mindset Shift That Changes Everything — Delayed Gratification
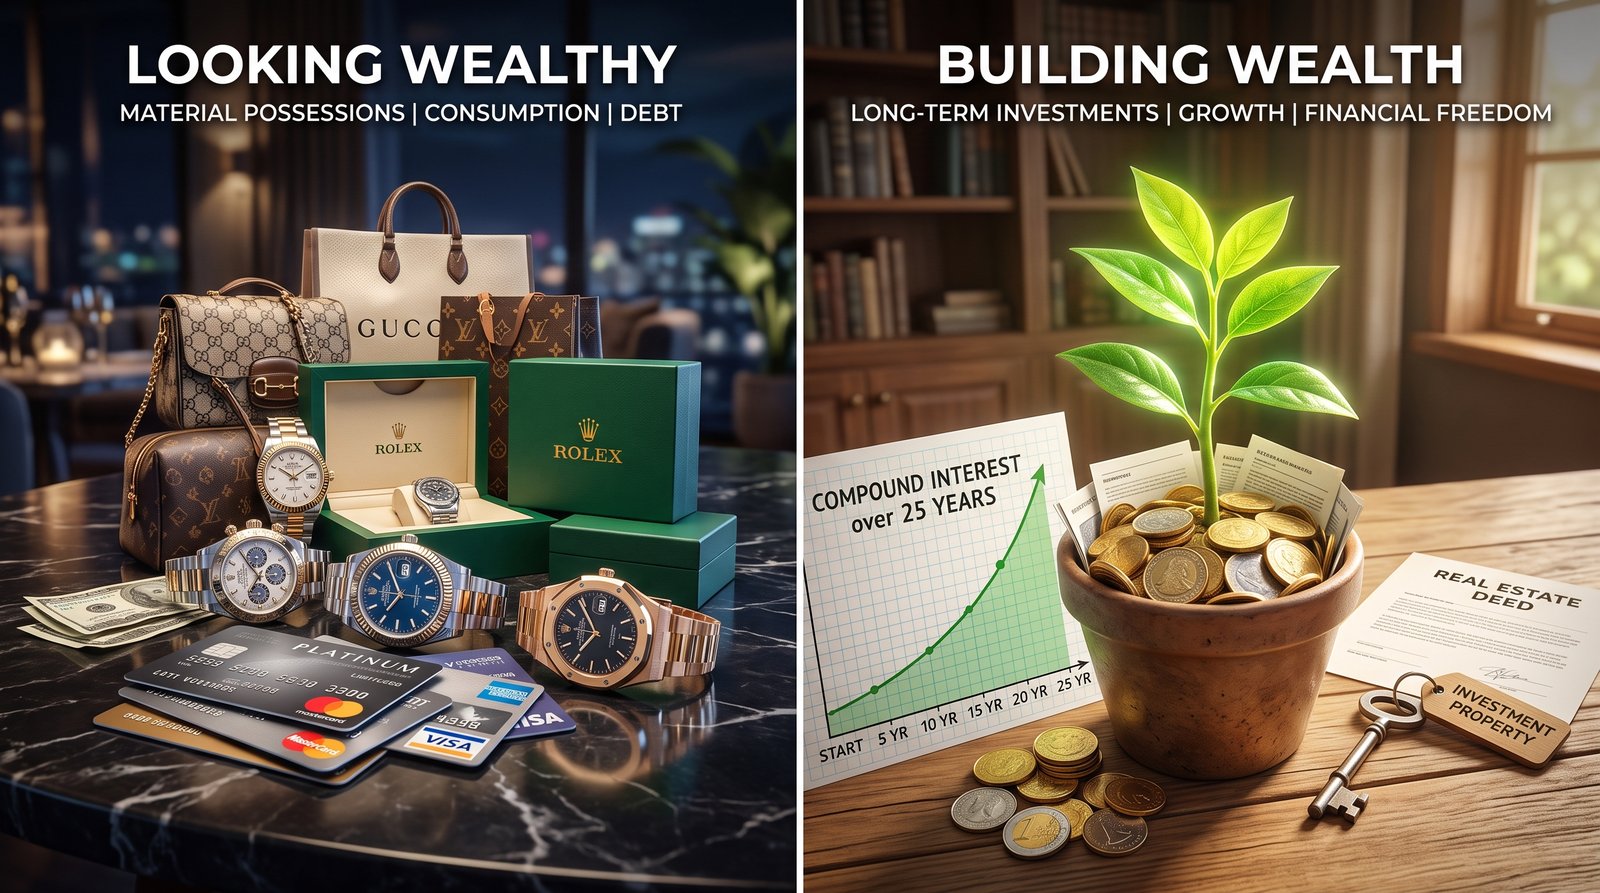
Let's keep one piece of advice in mind – if we can't afford to buy something twice, then we shouldn't buy it once. Such a statement seems pretty strict, but let us look into it more carefully. We don't talk about refusing from buying anything ever again in the future. Instead, we build up a reserve that will allow us to buy an item without being financially ruined by something unexpected. Most likely, the majority of those people who have money issues are not very good with numbers. The thing is that these people have natural instincts of receiving immediate benefits. Every new phone, any upgrades or trips that they cannot really afford – all of them are appealing. However, each dollar wasted on instant comfort is not multiplied for our future self. It is not about the feeling of guilt; it is all about the timing of our actions.
Those who create real wealth are not those who do not get any enjoyment out of their money. They get their enjoyment while using it, but only after they've met their basic necessities. The way they do things is by saving first and then spending whatever is left without feeling guilty. That is also the place from where the financial pressure arises – not due to low income, but due to a spending behavior that is not in line with the income. In other words, an individual making an average income can have better finances than one earning three times that amount.
The Three Numbers That Actually Matter
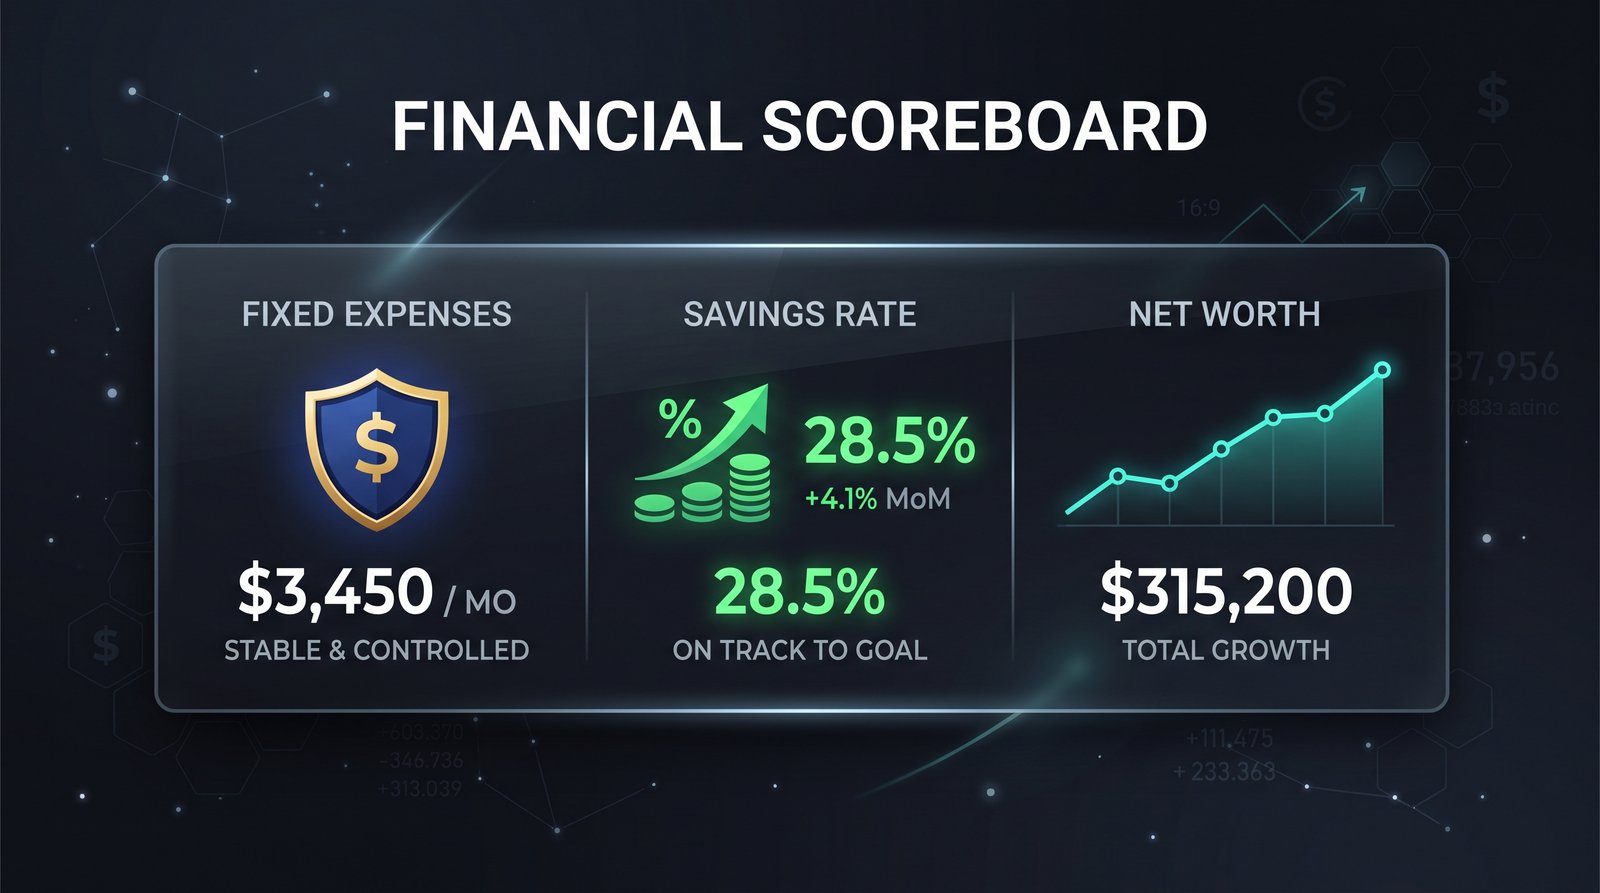
Forget complicated spreadsheets for a second. There are really just three numbers worth tracking if you want to know where you stand financially. First, your fixed expenses — rent, bills, insurance, anything that doesn't change month to month. Second, your savings rate — the percentage of income you're actually putting aside, not just what's left over by accident. Third, your net worth — everything you own minus everything you owe. Most people obsess over their salary and completely ignore these three. But salary alone tells you nothing. Two people earning the same amount can have wildly different financial futures depending on these three numbers alone.
This is important for all the following reasons. Fixed costs tell you exactly how much leeway you have in terms of cash flow. When your fixed costs constitute 80 percent of your earnings, you need only a single bad month to be in trouble regardless of how high your income. Savings percentage indicates discipline and not income level because if you can save 20 percent from a modest salary then you are in a better position than someone who can save 2 percent from a big one. Lastly, net worth is the score card and not what your car is or how your social media account looks like. It's the bottom line number which grows silently in the background.
- Track fixed expenses to know your real breathing room
- Measure your savings rate, not just your income
- Watch net worth as your true financial scoreboard
- Keep your investing simple — one to three funds is plenty
- Never borrow money for things that lose value
- Give investments decades, not months, to actually work
Investing Doesn't Need to Be Complicated (And Shouldn't Be)
People often stay away from investing because it seems like a lot to handle. There are many stocks to choose from and the terms can be confusing. We are always hearing about the market going down.. The thing that people who are new to investing do not understand is that the easiest way is usually the best way. You do not need to buy a lot of stocks. A few funds that follow the market can do better than most other investments over time. You also do not need to watch the market every day to make choices. This is not a fix. It is actually what the experts say works best. Trying to be smarter than the market by picking the stocks or trying to buy and sell at the right time usually does not work, even for people who do this for a living. Doing things in an steady way is usually better, than trying to be clever. This also connects to another thing that people often get wrong. You should never borrow money to buy things that will be worth soon. For example a car, clothes or furniture. These things are worth less soon as you buy them. If you borrow money to buy these things you will have to pay interest on something that's worth less and less which does not make sense. If you do not have the money to pay for something that will lose value you should probably. Not buy it now.
Playing the Long Game — Why Patience Beats Timing
The best thing about investing in the long-term is that the longer you invest, the lower the possibility of losing money. There will be fluctuations in the market within one week, one month, or even one year, which can be quite frightening. However, once you expand the timeline to fifteen or twenty years, there will be more chance that everything will turn out to be good for you. This is the reason why initial savings are so important compared to initial returns on investment. At the early stage of the process, all returns depend only on the amount of money saved, but not on wise investments. Although a portfolio that grows quickly will grow, its value will remain low until the years of saving allow you to accumulate the necessary amount of capital. It is the same reason why investing should almost never become an event. You just have to buy steadily, hold your investments and never go looking for any changes or information.
The Traps That Quietly Wreck People's Finances
There are two subtle habits that sabotage most of people’s financial success. First, comparing yourself to other people and what they have on social media can ruin all of your efforts. Vacation pictures and shiny cars reveal nothing about the financial situation of that person. Many people who are posting fancy pictures about themselves have huge debts. The problem is that you compare your reality with the polished picture of life of somebody else. Second, the desire to look like a millionaire instead of being one is another bad habit that ruins financial success. The example is when a person earns a decent salary but spends money on the looks of the exterior only, such as having a fancy car and buying branded clothes. In the end, this person will have nothing but debt and no savings at all. True rich people are those who drive old but comfortable cars and save enough money in their bank account.
Finally, in conclusion, one can say that good financial advice is not something absolute and universal. While one piece of advice may be great for a young man who has no children or wife, another person with different risk tolerance, steady or fluctuating income, and other characteristics will require some other kind of advice. One may recommend investing all your money into stocks and bonds, but if such an investment keeps you awake at night whenever there are some market fluctuations, this is not the right choice of advice for you personally. Good advice is not just about following what others say; it is more about the ability to filter out what is relevant to you.
Conclusion
None of this is difficult, which is the whole point. Follow your numbers. Make investing easy. Don't incur debt on assets that depreciate. Be aggressive at the beginning, patient at the end, and don’t compare your chapter one to anyone else's chapter twenty. Money is not made by one great decision. It's made by small, tedious decisions that add up over time. If you implement just two or three of these lessons and start to apply them from now on, you will be light years ahead of those people who merely read about finance but never practice it.
Share this article: